- Crocs (NASDAQ: CROX) received an upgrade from Barclays to Overweight, signaling positive analyst sentiment for the footwear company.
- The company is driving revenue growth through product diversification, e-commerce investments, and strong international sales, particularly in Asia.
- Despite overall positive trends, North American demand remains a concern, with expected declines in direct-to-consumer sales.
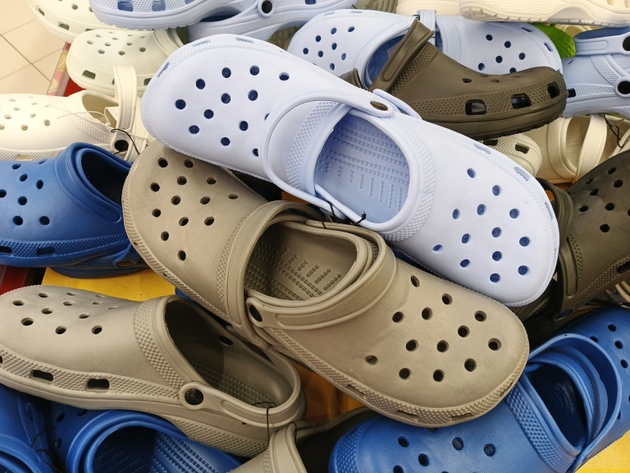
Crocs (NASDAQ: CROX) receives an upgrade from Barclays from Positive to Overweight, with shares trading at $117.54 when the upgrade is posted. Crocs makes casual footwear, best known for its clogs. It competes for customers through new styles, online sales, and international growth.
As highlighted by Zacks Investment Research, Crocs expands beyond its signature clogs with new designs, collaborations, and other footwear categories. The company also invests in e-commerce and digital marketing. At the same time, it works on sourcing and inventory management to limit the effect of rising costs on profit margins.
International sales provide a key source of growth. In the second quarter of 2026, Crocs brand international revenue rises 7% from a year earlier, led by double-digit growth in China, India, and Japan. This helps offset weaker North American demand and lifts quarterly Crocs brand revenue above $1 billion for the first time.
Crocs opens about 160 brand-only stores and kiosks, including 34 company-operated stores internationally. As highlighted by Zacks Investment Research, the company raises its 2026 Crocs brand revenue growth outlook to 2%–3%, with international markets expected to lead.
North America remains a concern. As highlighted by Proactive Investors, Bank of America (NYSE: BAC) expects third-quarter direct-to-consumer sales there to fall 7%, compared with a 5% decline in the Visible Alpha consensus forecast. A change in how sales to a large partner are recorded shifts revenue from direct-to-consumer to wholesale, making the reported direct-to-consumer figure weaker.