CNH Industrial (NYSE: CNH) Stock Analysis: Evercore Upgrade Fuels Farm-Cycle Optimism
- CNH Industrial (NYSE: CNH) is a global manufacturer of agricultural and construction equipment whose performance is closely tied to commodity prices, farm income, and global economic cycles.
- Evercore ISI upgraded CNH Industrial from “In Line” to “Outperform” and raised its price target from $12.50 to $18, reinforcing the more optimistic outlook recently expressed by Robert W. Baird.
- CNH’s investments in precision technology, cost efficiencies, and dealer-inventory reductions could support long-term growth, although weak agricultural-equipment demand and elevated costs remain important near-term risks.
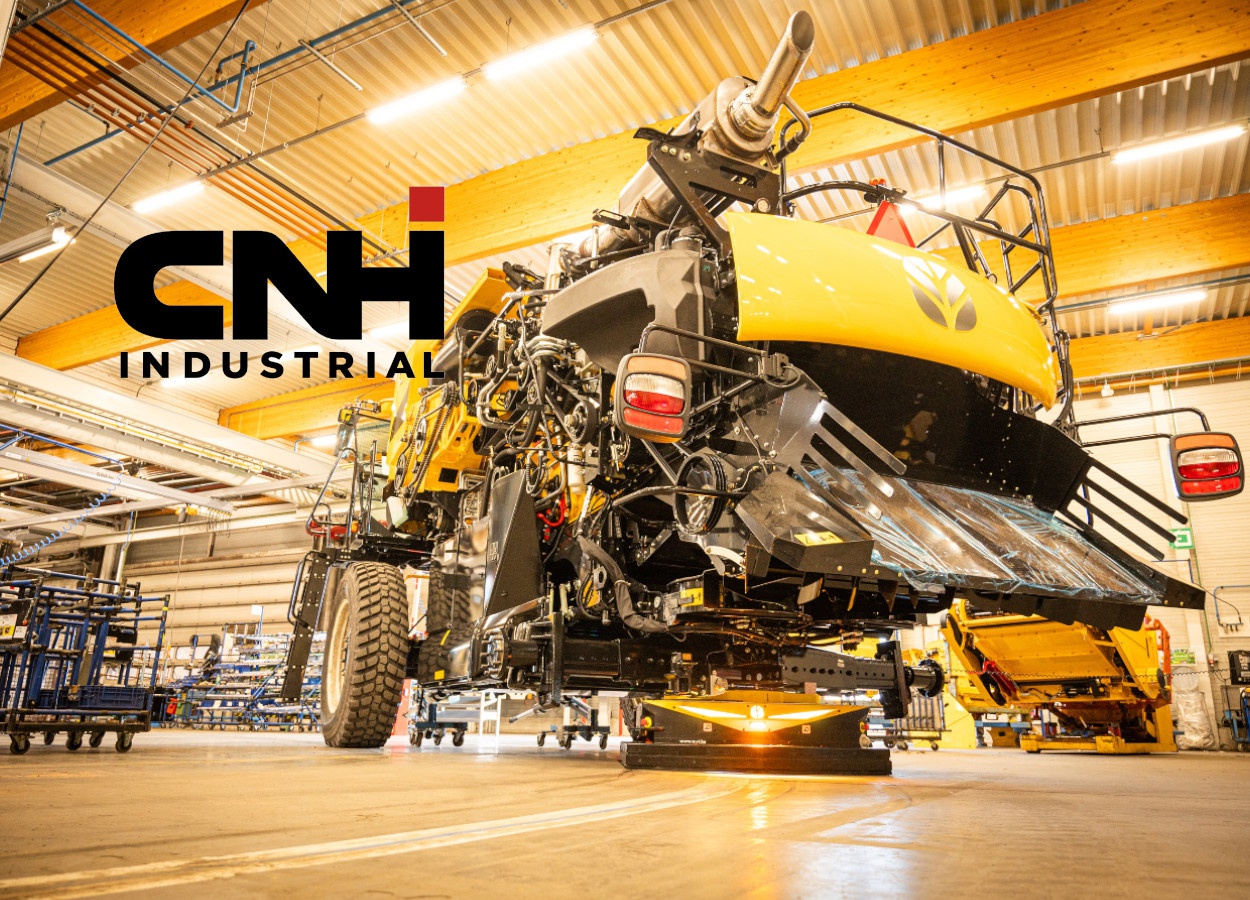
CNH Industrial (NYSE: CNH) is a global company that designs and manufactures agricultural and construction equipment. Through brands such as Case IH, New Holland Agriculture, CASE Construction Equipment, and New Holland Construction, the company supplies machinery, technology, and services to farmers and construction customers worldwide.
On September 2, 2026, Evercore ISI upgraded CNH Industrial from “In Line” to “Outperform” and raised its price target from $12.50 to $18. Based on the stock’s September 2 closing price of $13.65, the new target represented potential upside of approximately 31.9%.
The Evercore upgrade followed another bullish analyst action. On August 31, Robert W. Baird upgraded CNH Industrial from “Neutral” to “Outperform” and raised its price target from $11 to $15. The firm cited expectations for improving agricultural fundamentals, stronger farmer margins, and a potential recovery in farm-equipment demand beginning in 2027.
Other analysts remain more cautious. Citigroup maintained a “Buy” rating with a $13 price target, while Truist Financial reiterated a “Buy” rating and lowered its target from $16 to $15. Sanford C. Bernstein maintained a “Market Perform” rating with an $11 target, indicating that expectations for CNH still vary considerably across Wall Street.
CNH shares gained 9.2% on September 2, closing at $13.65 after reaching a new 52-week intraday high of $13.89. The rally reflected growing optimism that the agricultural-equipment downturn may be approaching its later stages.
CNH’s longer-term strategy also supports the bullish case. The company plans to expand its precision-technology business, improve operational efficiency, reduce dealer inventories, and strengthen its agricultural-equipment margins. CNH expects precision-technology sales to nearly double as a percentage of Agriculture net sales by 2030.
However, investors should balance these opportunities against continuing risks. Agricultural-equipment demand remains weak in several markets, while low crop prices, high farming costs, tariffs, and elevated dealer inventories could continue to pressure sales and margins. CNH expects industry demand to begin recovering in 2027, but the timing and strength of that recovery remain uncertain. Reuters