Key takeaways
- Goldman Sachs maintains a Buy rating for Xylem (NYSE:XYL), setting a price target significantly above the current share price.
- The company reported mixed third-quarter 2026 results, with adjusted earnings per share missing consensus estimates despite a year-over-year increase, and revenue also falling short.
- Despite challenges like cautious customer spending, orders showed strong growth, though Xylem has revised its full-year 2026 outlook downwards for both revenue and adjusted earnings.
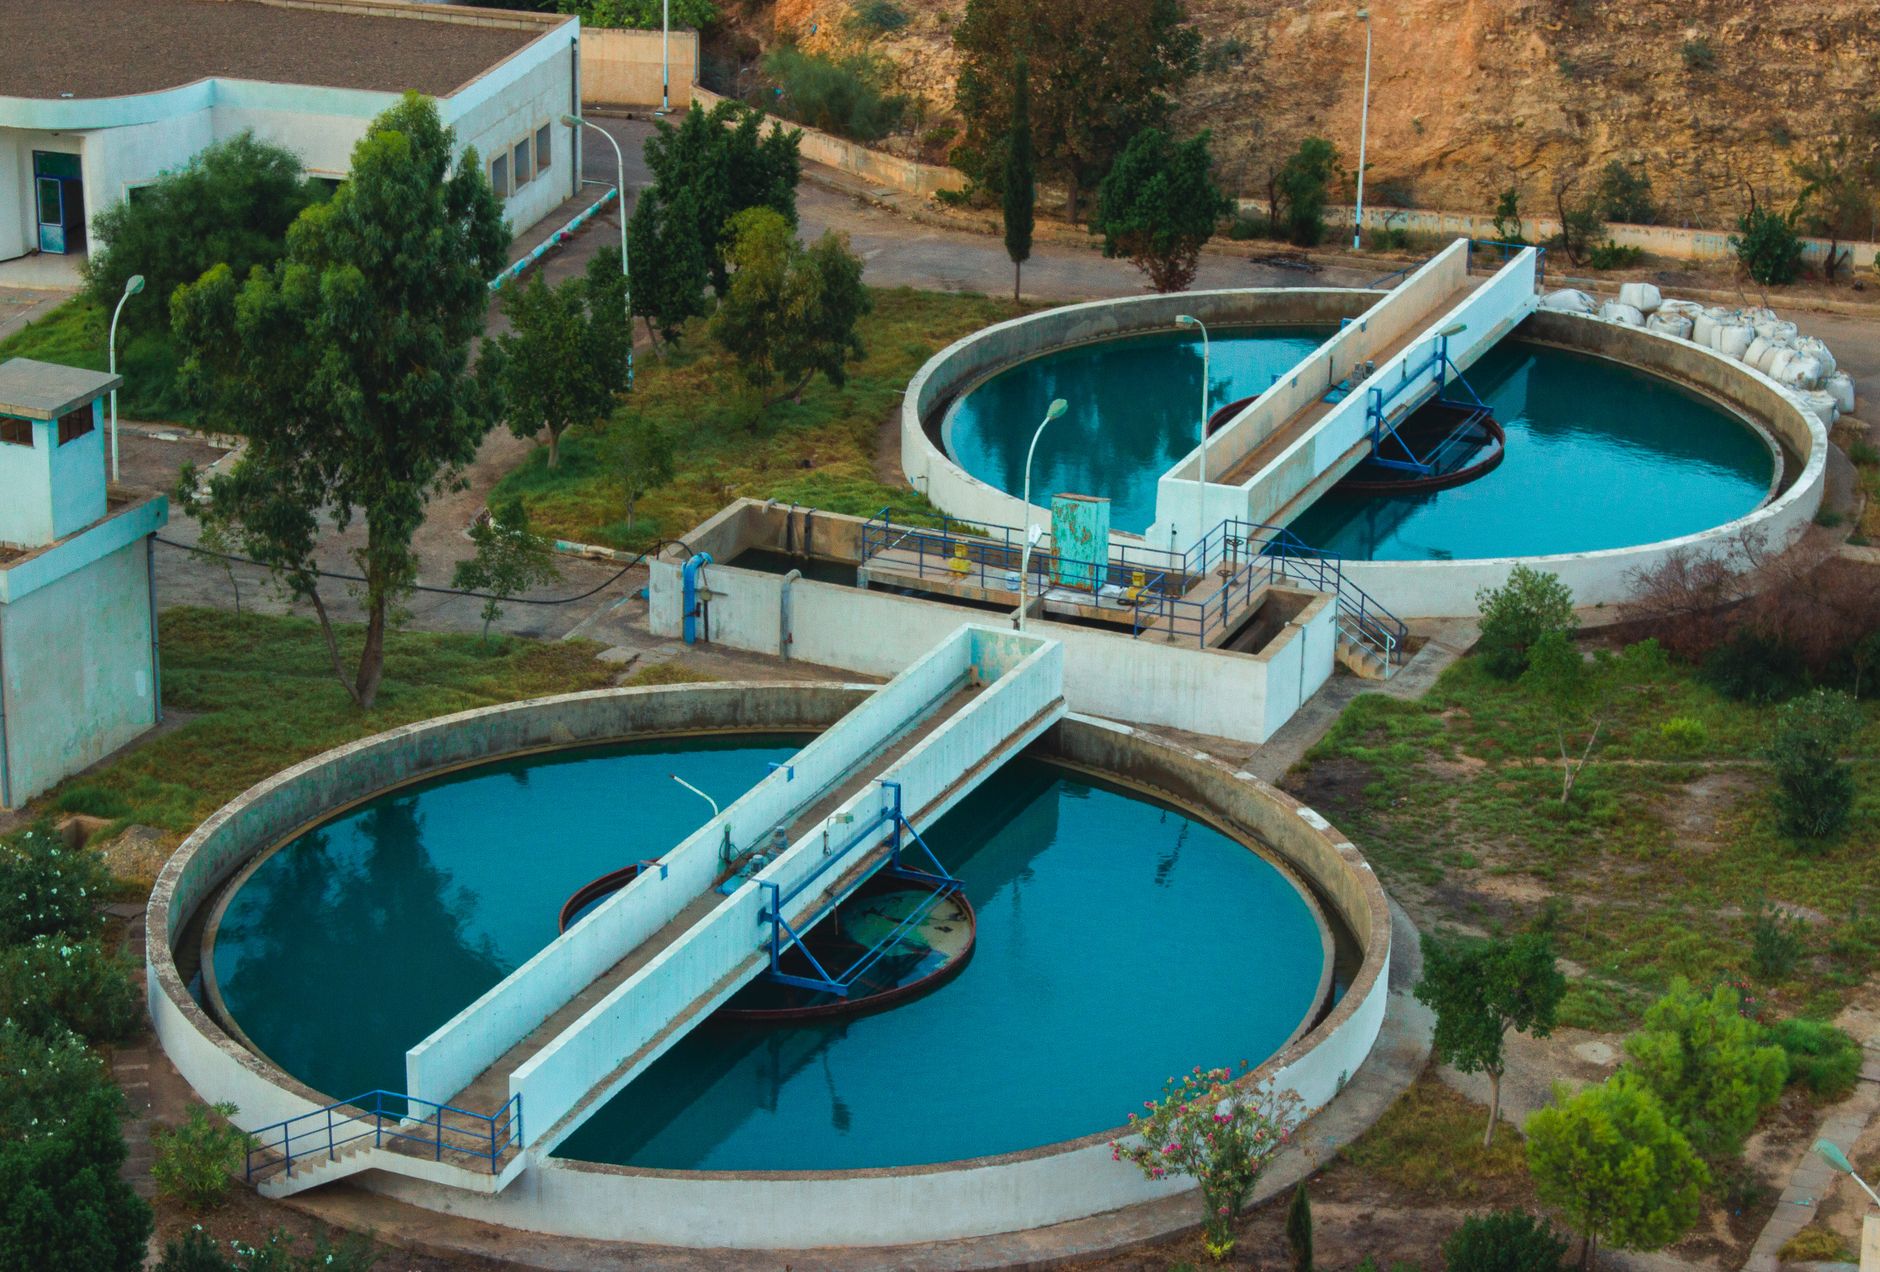
Xylem makes equipment and technology used to move, treat, and measure water. Brian Lee of Goldman Sachs reiterates a Buy rating and sets a $138 price target. With Xylem trading at $92.86 at the time of publication, the target is about 48.6% above the share price.
The gap between the price and the target comes as Xylem reports a mixed third quarter in 2026. As highlighted by Zacks, adjusted earnings rise 5.1% from a year earlier to $1.44 per share, but fall short of the $1.47 consensus estimate. Adjusted earnings exclude certain costs to help investors compare operating results.
Revenue falls 3% to $2.22 billion and also misses estimates. Metering affordability pressures and the timing of customer projects weigh on sales. As highlighted by Business Wire, Xylem also points to more cautious customer spending as it announces strategic actions intended to support growth.
Orders provide a stronger signal of future demand, rising 7% to $2.33 billion. Organic order growth is 10%, which measures growth without the effects of acquisitions and currency changes. Xylem lowers its 2026 outlook to $8.95 billion in revenue and adjusted earnings of $5.40–$5.45 per share.
Xylem is down $15.38, or 14.21%, at $92.86. It trades between $92.76 and $102.77 during the day, near the low end of its 52-week range of $92.61 to $154.27. Trading volume is 10.22 million shares, and its market value is approximately $21.68 billion.