Key takeaways
- Analyst Jasper Hellweg sets a $1,550 price target for Eli Lilly, indicating a potential 12.9% gain from its current trading price of $1,373.
- The pharmaceutical giant reported robust Q3 2026 results, with revenue soaring 39% to $24.40 billion and adjusted earnings reaching $7.48 per share, significantly exceeding estimates.
- Key growth drivers include Mounjaro and Zepbound sales, with future potential from pipeline assets like Foundayo and Retatrutide, though the stock trades at a premium with 37.4 times expected earnings.
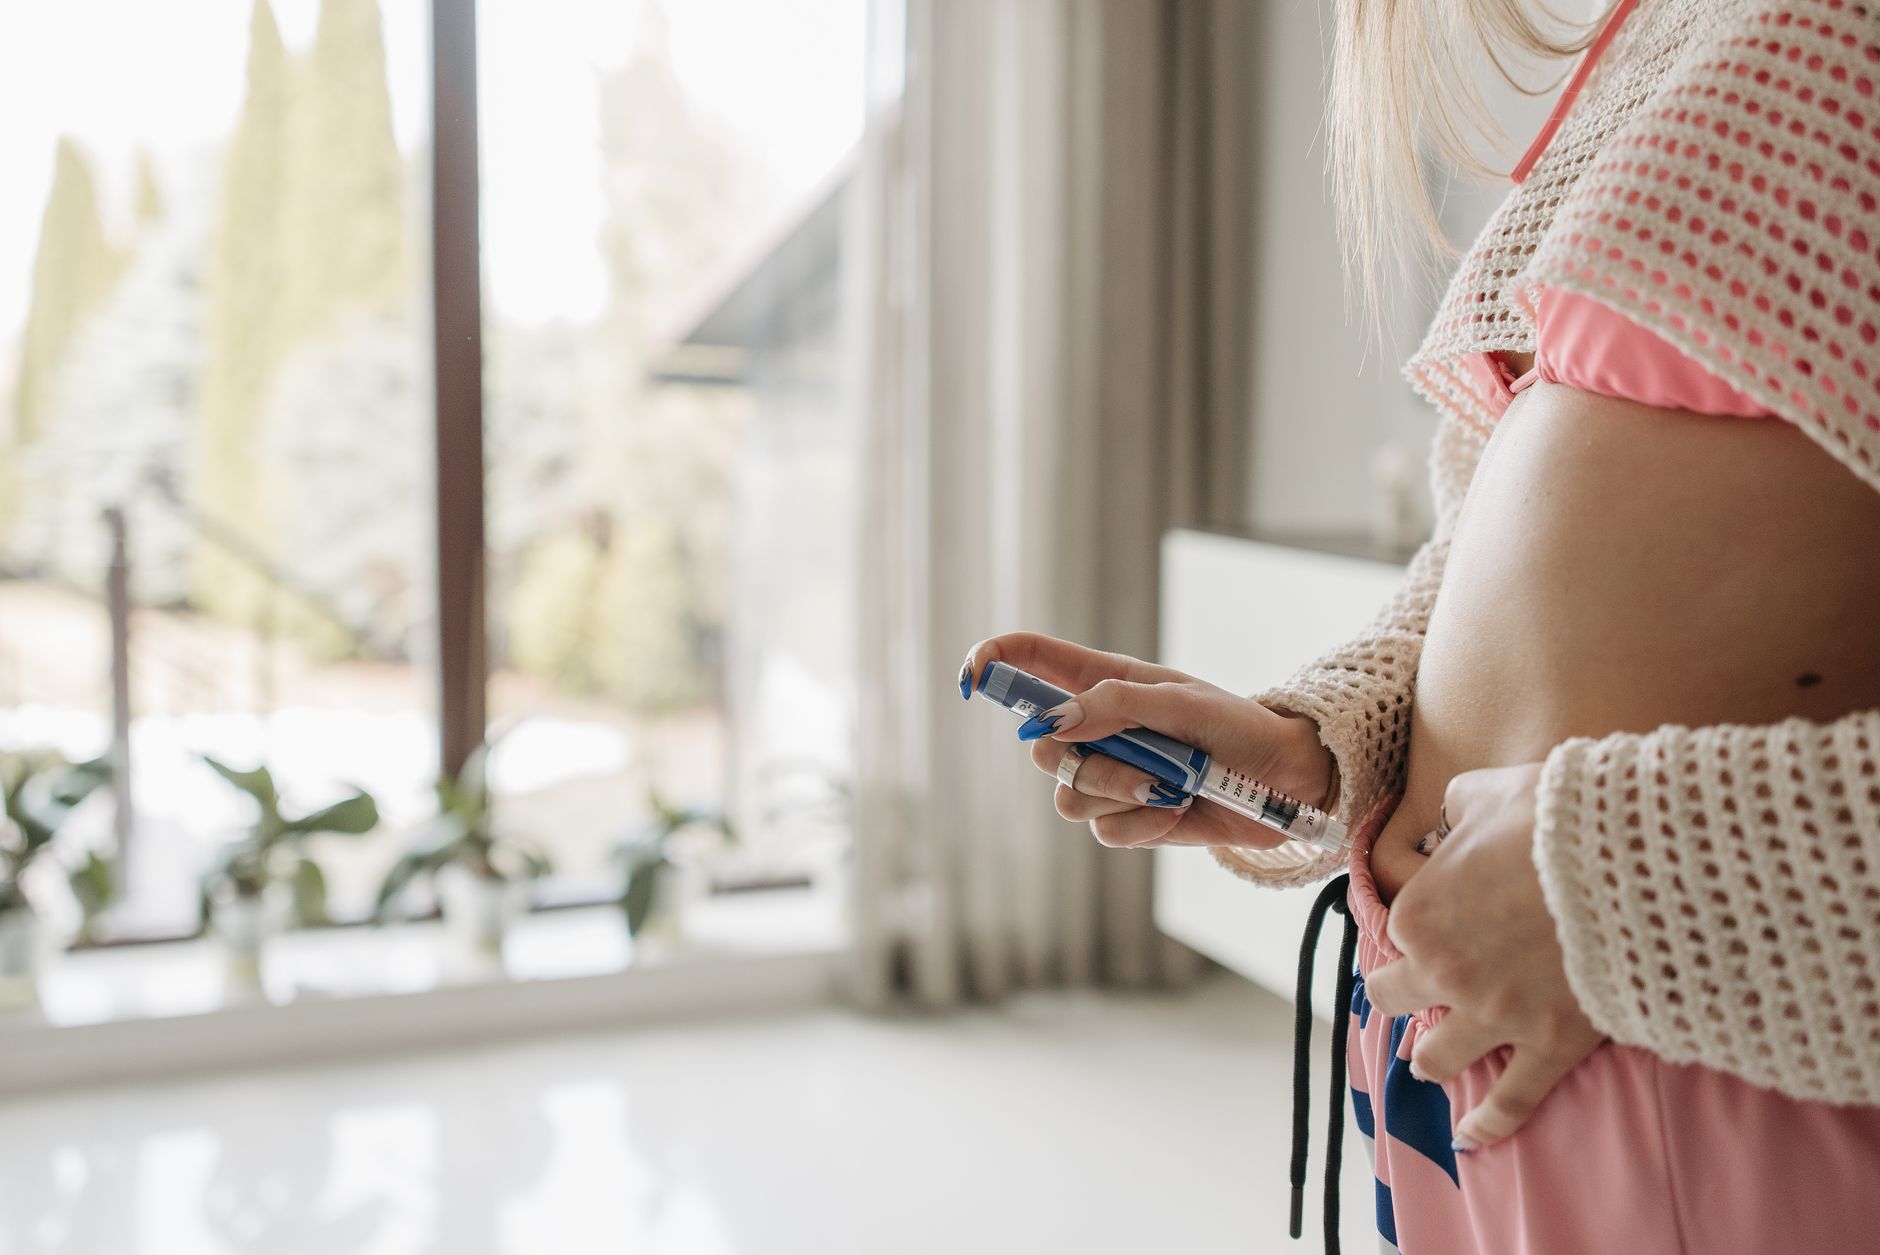
Eli Lilly (NYSE: LLY) makes medicines for diabetes and obesity, including Mounjaro and Zepbound. Jasper Hellweg of Argus Research sets a $1,550 price target for the stock. At the stated trading price of $1,373, reaching that target would mean a gain of about 12.9%.
The target follows strong third-quarter 2026 results. Revenue rises 39% to $24.40 billion, above the $22.11 billion estimate. Mounjaro sales grow 65%, while Zepbound sales grow 49%. These products are the main drivers of Lilly’s revenue growth.
As highlighted by Zacks, adjusted earnings reach $7.48 per share, up 7% from a year earlier and 39% above the $5.38 estimate. Lilly raises its full-year revenue outlook to $91 billion–$92 billion, and shares rise about 4% in premarket trading after the results.
The results also include one-time benefits, including $410 million in Jardiance milestone payments and favorable changes to U.S. rebate and discount estimates. These items add to the quarter’s results but may not recur at the same level.
As highlighted by Seeking Alpha, Foundayo, Retatrutide and the Medicare Bridge program could provide further growth. Lilly trades at 37.4 times expected earnings and 13.5 times expected sales. These ratios compare its share price with projected profit and revenue, showing how much investors pay for the company’s expected results.